Fewer multifamily units are entering the market which is good news for multifamily of all types. The number of new multifamily units projected to enter the market in the future can be estimated by the number of construction starts (see chart below). The number of construction starts has been relatively low since the beginning of 2024, which means few units have been entering the market. However, even with fewer multifamily units entering the market, occupancy and rents were still difficult to maintain in 2024-2025 because of the massive oversupply of units created in 2022 through 2023. Fortunately, absorption remained strong (measured by net absorption) which means many of the new multifamily units were filled. By the end of 2024, the supply-demand balance was effectively returned to normal levels. However, in 2025, a new culprit was dampening rents and occupancy, immigration policy, which primarily hurt Class C properties where many undocumented immigrants were living. Even if a property did not have undocumented immigrants, the overall drop in occupancy and rents meant that all Class C properties were competing for fewer residents. Now that the effects of the immigration policy seem to have stabilized, there is a stronger case for occupancy to recover across the board. We are optimistic for a recovery in Class C properties, but keep in mind we may not see meaningful improvements for a few months as we change staff and enter a slower leasing season.
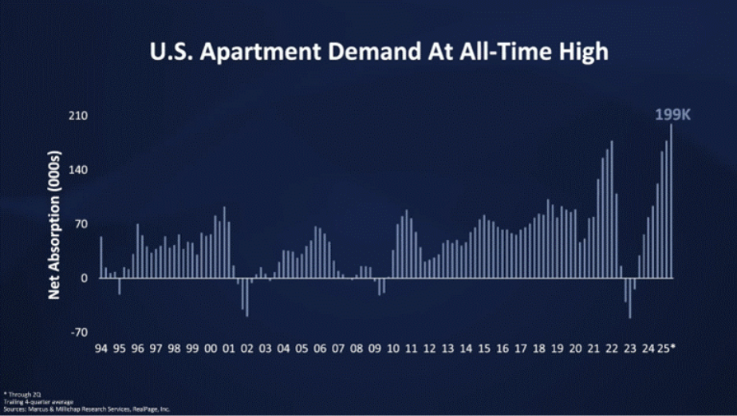
CHART: The impact from 2025 immigration policy disrupted demand in Class C space so much that 2025 marks the first summer where rents declined, as landlords lowered rents drastically in order to maintain occupancy. SOURCE: Jay Parsons, Waymaker, RealPage.
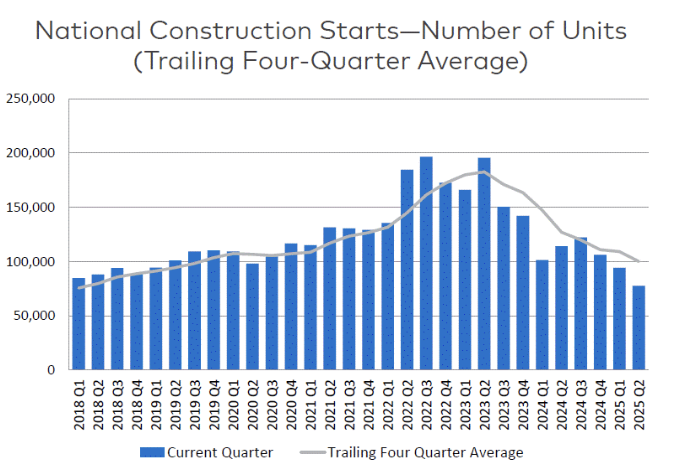
CHART: Most of the massive oversupply of units that were delivered in 2023-2024 have now been filled. This should bring the previous supply-demand imbalance back to more normal levels.
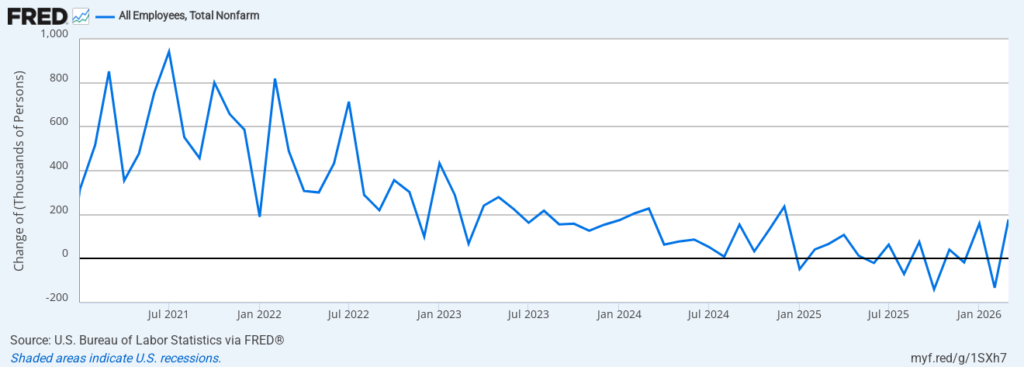
CHART: Construction starts have continued to decline in 2025, indicating fewer new multifamily units will enter the market over the next year or so. This could indicate a recovery in occupancy and rents across multifamily of all types